

Highlights
Trading continues to be weak but not terrible.
Planned return to LSD sales growth, MSD EBIT growth.
No profit reset, but drastic changes under the hood.
U.S. is the main challenge, sales to stabilize in FY29.
Re-rating potential from ~15x P/E, 5%+ FCF Yield.
Introduction
Diageo released FY26 results and held its first investor day with Dave Lewis as CEO last Thursday (August 6). Shares rose 5.6% that day, continuing their rise since the March 24 trough, but remain 12.9% lower than a year ago:
Diageo Share Price (Last 1 Year)
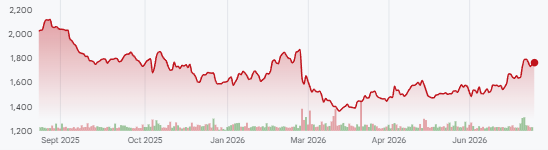
Source: Google Finance (14-Aug-26).
Diageo is a mid-sized position in our “Select 15” model portfolio, where it has been since the start of 2023 and currently shows a 34% loss. We originally initiated our Buy rating on Diageo in July 2019.
New CEO Dave Lewis has set out a plausible plan to return to mid-single-digit organic EBIT growth. There will be some drastic operational changes, but no profit reset. The 5%+ Free Cash Yield and ~15x P/E seem cheap in this context.
(The rest of this article is for paid subscribers only, but unlocking it costs just $10; you can see a free sample of our research here.)